When you reach a certain age, typically 72 years old, you are required to start withdrawing money from your 401k account. This is known as the required minimum distribution (RMD) and failing to do so can result in hefty penalties. To help you navigate this process, there is a 401k minimum distribution chart that outlines the amount you are required to withdraw each year based on your age and account balance.
The 401k minimum distribution chart provides a clear guideline on the minimum amount you must withdraw from your retirement account each year. The chart takes into account your age and account balance to determine the required distribution amount. It is important to consult this chart annually to ensure you are meeting the IRS requirements and avoiding any penalties.
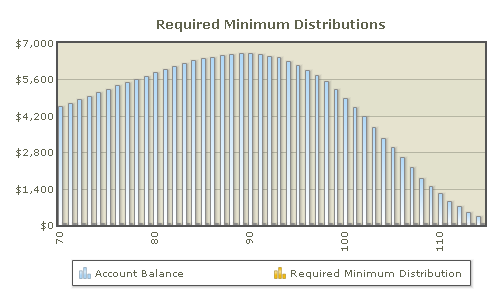
For example, if you are 72 years old with a $500,000 401k balance, the minimum distribution amount would be calculated based on the IRS life expectancy table. This amount may vary each year as your age and account balance changes, so it is crucial to stay informed and plan accordingly.
Failure to withdraw the required minimum distribution can result in a 50% penalty on the amount that should have been withdrawn. This can significantly impact your retirement savings and financial well-being. By following the 401k minimum distribution chart and staying on top of your withdrawals, you can avoid these penalties and ensure a smoother retirement process.
It is important to note that you are allowed to withdraw more than the minimum distribution amount if you choose to do so. This can be beneficial if you need extra funds for expenses or if you want to reduce your tax liability. However, it is crucial to strike a balance between withdrawing enough to meet the IRS requirements and not depleting your retirement savings too quickly.
In conclusion, the 401k minimum distribution chart is a valuable tool for retirees to ensure they are meeting the IRS requirements for withdrawals from their retirement accounts. By understanding and following this chart, you can navigate the RMD process with ease and avoid costly penalties. Consult with a financial advisor to help you create a withdrawal strategy that aligns with your retirement goals and financial needs.